Refinancing Done Right: A Strategic Framework for Reducing Debt Without Undermining Your Financial Future
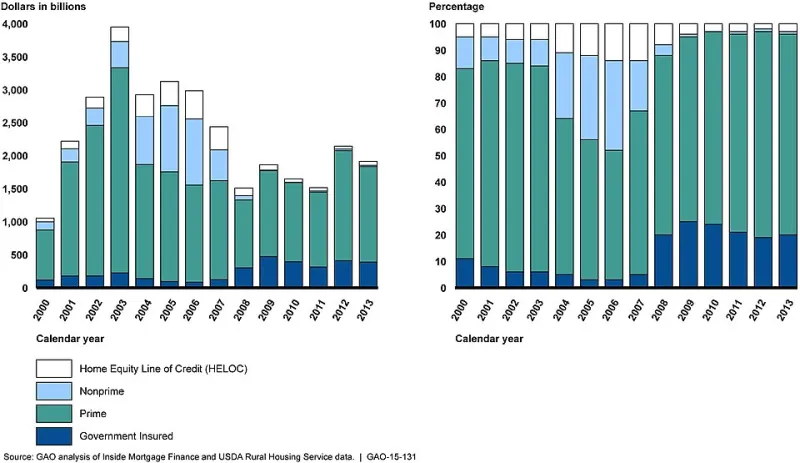
Photo: U.S. Government Accountability Office, Public domain, via Wikimedia Commons
Refinancing carries an almost universally positive reputation in popular financial culture. Lower your rate. Reduce your payment. Free up cash. The marketing language around refinancing tends to emphasize the immediate relief it can provide, and that relief is real — under the right circumstances. What receives far less attention are the conditions under which refinancing quietly extends your debt, increases your total interest paid, and leaves you in a structurally weaker financial position than when you started.
Understanding the difference between strategic refinancing and reflexive refinancing is one of the more consequential distinctions in personal finance. This guide is designed to help you develop that understanding so that any refinancing decision you make is grounded in a complete picture of the costs and benefits — not just the appeal of a lower monthly payment.
The Core Principle: Total Cost, Not Monthly Payment
The single most common error in refinancing decisions is evaluating success by the reduction in monthly payment rather than the reduction in total cost. These two measures frequently point in opposite directions.
Consider a homeowner with fifteen years remaining on a thirty-year mortgage at a rate of 6.5 percent. She is offered the opportunity to refinance into a new thirty-year mortgage at 5.75 percent. Her monthly payment drops by a meaningful amount. The move feels like an obvious win.
But she has also reset her amortization clock. Instead of paying off her home in fifteen years, she is now committed to thirty more years of payments. The lower rate does not offset the additional fifteen years of interest she will pay over the life of the new loan. Depending on her remaining balance, she may end up paying significantly more in total interest than she would have by simply continuing on her original schedule.
The appropriate question is not "Does this lower my payment?" but rather "Does this reduce my total cost of borrowing, and does that reduction align with my broader financial goals?"
When Refinancing Genuinely Makes Sense
Refinancing is most clearly advantageous in several well-defined scenarios.
Rate reduction with a maintained or shortened term. If you can refinance into a materially lower interest rate without extending your repayment timeline — or while actually shortening it — the math is likely to work in your favor. The break-even calculation here is straightforward: divide the total closing costs by your monthly savings to determine how many months it takes to recoup the cost of refinancing. If you plan to remain in the home or retain the loan beyond that break-even point, refinancing makes financial sense.
Transitioning from an adjustable rate to a fixed rate. Borrowers who took on adjustable-rate mortgages during a low-rate environment and are approaching their adjustment period may have strong reasons to lock in a fixed rate, even if that rate is modestly higher than their current one. Predictability has genuine value in financial planning, and the risk of rising payments can outweigh the cost of refinancing.
Consolidating high-interest debt into a lower-rate instrument. Paying off credit card balances or high-rate personal loans by refinancing into a lower-rate product can generate real savings — provided the underlying spending behavior that created the debt has been addressed. Consolidation that is not accompanied by a change in financial habits tends to result in the same high-interest balances being rebuilt alongside the new refinanced debt.
Common Misconceptions That Lead to Poor Decisions
Several persistent myths about refinancing deserve direct attention.
Misconception: A lower rate always means a better deal. Rate is one variable in a multi-variable equation. Term length, closing costs, prepayment penalties on the existing loan, and the remaining balance all affect whether a rate reduction translates into genuine savings.
Misconception: Cash-out refinancing is free money. When you take equity out of your home through a cash-out refinance, you are converting an asset into debt. That transaction carries a cost — both in the interest you will pay on the increased loan balance and in the reduced equity you hold in your home. Using cash-out refinancing to fund consumption rather than investment is a wealth-reducing strategy, not a wealth-building one.
Misconception: Refinancing your auto loan always saves money. Auto loans amortize quickly, and a large portion of the interest on any installment loan is paid in the early months. If you are two or three years into a five-year auto loan, refinancing may extend your term and increase your total interest even if the rate appears lower. The remaining balance and remaining term must be evaluated carefully.
Building a Refinancing Framework
A structured approach to evaluating any refinancing opportunity should address four questions.
First: What are the total costs of refinancing? Include origination fees, closing costs, any prepayment penalties on your current loan, and the cost of any required appraisals or inspections. A refinancing transaction with $6,000 in closing costs requires meaningful monthly savings to justify itself.
Second: What is the break-even point? Divide the total cost of refinancing by your monthly savings. If the break-even point is thirty-six months and you plan to sell your home in two years, refinancing is not advantageous regardless of the rate.
Third: What happens to your total interest paid over the life of the loan? Use an amortization calculator to compare the total interest you will pay under your current loan versus the refinanced loan. This number may be surprising.
Fourth: Does this decision serve your long-term financial goals? A refinancing that modestly reduces your monthly payment but extends your debt by ten years may feel like relief and function as a setback. Align the decision with where you want to be financially in five, ten, and twenty years.
The Role of Your Banker in the Refinancing Decision
One of the genuine advantages of working with a community bank is access to a financial professional who can walk through this framework with you rather than simply presenting you with a rate and an application. At Bear State Bank, our lending team approaches refinancing conversations as planning conversations — helping customers understand not just whether they qualify for a new loan, but whether taking that loan moves them closer to or further from their financial objectives.
Refinancing is a tool. Like any tool, its value depends entirely on how and when it is used. Applied with discipline and a clear understanding of the full cost picture, it can meaningfully reduce your debt burden and accelerate your path to financial stability. Applied reflexively in pursuit of short-term payment relief, it can quietly deepen the debt cycle it appears to resolve.
The difference lies in the quality of the analysis you bring to the decision — and the quality of the guidance you have access to when making it.