Your Financial Home Base: How Community Banking Anchors Every Stage of Your Life
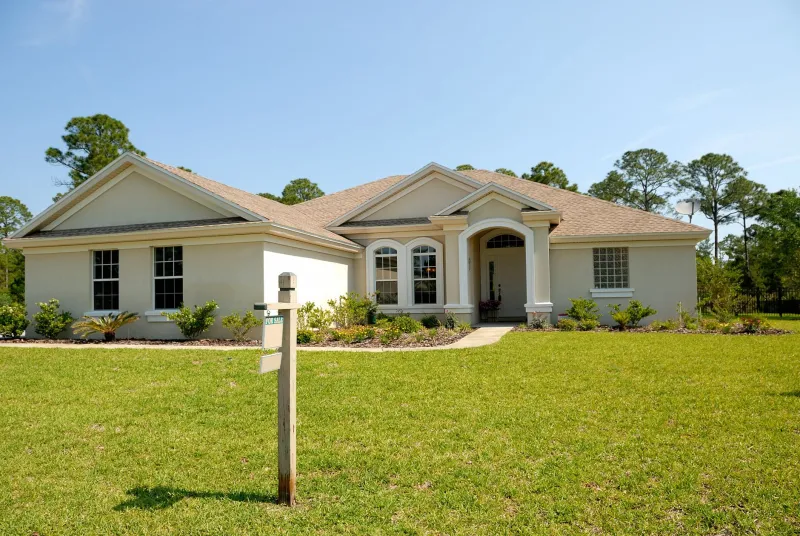
For most Americans, the word "home" carries two meanings simultaneously. It is the place where daily life unfolds — where families gather, routines are formed, and memories are made. It is also, for the majority of households, the single largest financial asset they will ever own. At Bear State Bank, we believe these two meanings are inseparable, and that serving one without acknowledging the other is a disservice to the people we are here to help.
Community banking exists precisely to bridge that gap — to treat your financial decisions not as transactions to be processed, but as chapters in an ongoing story that we are privileged to be part of.
Why Your Home Is the Center of Your Financial Universe
Data from the Federal Reserve consistently shows that homeownership represents the primary source of household wealth for middle-income Americans. Unlike a retirement account that remains largely invisible until you need it, your home is a living, breathing part of your daily experience. It appreciates over time, generates equity that can be accessed strategically, and serves as collateral for financial opportunities you may not yet have considered.
But a home is also a source of ongoing financial obligation. Property taxes, insurance premiums, maintenance costs, and mortgage payments do not pause when the economy softens or life takes an unexpected turn. This is why having a trusted banking partner — one who understands your local market and your personal circumstances — is not a luxury. It is a practical necessity.
Getting Into Your Home: The Mortgage Journey
For most buyers, the path to homeownership begins with a mortgage. The mortgage landscape can feel overwhelming, particularly for first-time buyers navigating a market shaped by fluctuating interest rates, competitive inventory, and a seemingly endless list of loan products.
At a community bank like Bear State Bank, the mortgage process looks and feels different from what you might experience at a large national institution. Your loan officer is not a voice on a distant call center line. They are a neighbor — someone who understands the neighborhoods you are considering, the price dynamics of your local market, and the specific programs that may be available to buyers in your region.
Conventional loans, FHA loans, USDA rural development programs, and VA loans each carry different eligibility requirements, down payment thresholds, and long-term cost profiles. A community banking relationship gives you access to guidance that helps you select the right instrument for your situation rather than the product that is easiest to process.
Building Equity and Putting It to Work
Once you are in your home, the financial conversation does not end — it evolves. Each mortgage payment you make shifts a portion of your monthly obligation from interest toward principal, gradually increasing the equity stake you hold in your property. Over time, this equity becomes a meaningful financial resource.
Home equity lines of credit (HELOCs) and home equity loans allow qualified homeowners to access a portion of that accumulated value for purposes ranging from home improvement projects to debt consolidation, educational expenses, or small business investment. These products carry their own risk profiles and should be approached with clear purpose and realistic repayment planning.
At Bear State Bank, our lending team takes the time to walk through the implications of equity-based borrowing with you — not simply to close a loan, but to ensure that the financial decision you are making today does not create unnecessary pressure tomorrow.
Protecting What You Have Built
Homeownership also introduces a set of risks that require active management. Homeowners insurance is the most visible layer of protection, but it is rarely sufficient on its own. Flood coverage, umbrella liability policies, and title insurance each address categories of risk that standard policies may not cover.
Beyond insurance, protecting your home financially means maintaining an emergency fund capable of absorbing unexpected repair costs, avoiding over-leveraging your equity, and keeping your credit profile in good standing so that refinancing options remain accessible when interest rate conditions improve.
Community banks are well-positioned to help customers think through these protective measures holistically. Because we maintain ongoing relationships with our customers rather than processing them as one-time transactions, we are more likely to notice when a financial plan has gaps — and to raise that conversation proactively.
Planning for What Comes Next
For many homeowners, there comes a point when the home that once fit perfectly begins to feel either too large or too small. Empty nesters may find themselves maintaining square footage they no longer need. Growing families may find that a starter home has reached its limits. Retirees may begin to evaluate whether downsizing could free up capital to support a more comfortable retirement.
Each of these transitions involves significant financial decisions that extend well beyond the real estate transaction itself. The proceeds from a home sale, the timing of a purchase, the tax implications of capital gains, and the impact on estate planning all intersect in ways that require careful coordination.
This is where a long-standing banking relationship proves its value. When your banker knows your history — your savings patterns, your debt management approach, your financial goals — they can offer context that a new institution simply cannot provide.
Home as a Reflection of Financial Health
Ultimately, your home is one of the most accurate reflections of your overall financial health. The decisions you make about buying, financing, maintaining, leveraging, and eventually selling or passing on your property reveal a great deal about your financial habits, your planning horizon, and your relationship with risk.
At Bear State Bank, we take that reflection seriously. Our role is not simply to process your mortgage application or open a savings account. It is to be a consistent, knowledgeable presence across every financial chapter your household navigates — from the excitement of a first purchase to the complexity of retirement planning and generational wealth transfer.
Community banking, at its best, is not a product category. It is a relationship built on trust, local knowledge, and a genuine commitment to the financial well-being of the people and places we serve. Your home deserves nothing less.