Banking Through Every Chapter: How a Community Bank Grows With Your Family Across Generations
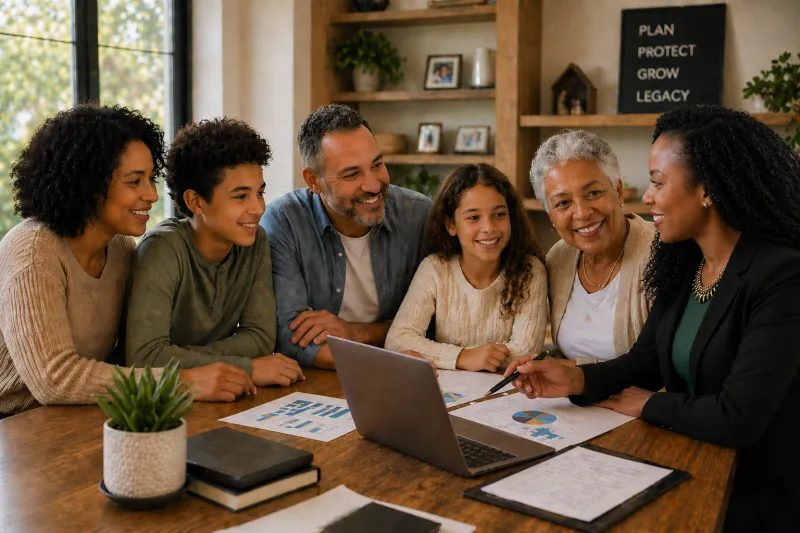
Photo: multigenerational family meeting with community bank financial advisor, via www.growthprotectionsecurity.com
Wealth is rarely built in a single transaction or during a single season of life. It accumulates gradually, through disciplined habits established in young adulthood, compounded by the financial decisions made during the high-earning middle years, and ultimately preserved and transferred through deliberate planning in retirement. Each of those phases presents distinct challenges, distinct opportunities, and a distinct need for financial guidance that reflects the realities of that particular moment.
National banks, for all their technological sophistication, tend to deliver standardized products to standardized customer profiles. A twenty-three-year-old opening her first checking account and a sixty-seven-year-old coordinating an estate plan may both receive a sleek mobile app and a toll-free number. What they rarely receive is a banker who knows them by name, understands their family circumstances, and can offer counsel that connects their current situation to their long-term trajectory.
At Bear State Bank, the multigenerational family is not an abstraction—it is a relationship we have had the privilege of serving, in many cases, across three and four generations. This article explores how community banking addresses the distinct financial needs of every chapter in a family's life.
Young Adults: Establishing the Foundation
The financial decisions made between the ages of eighteen and thirty have an outsized influence on long-term wealth accumulation, yet this demographic is frequently underserved by institutional banking. Products are often either too basic to be educational or too complex to be accessible.
For young adults, the most valuable thing a community bank can offer is not a particular product—it is access to a real conversation. At Bear State Bank, a first-time checking or savings account customer is not simply handed a debit card and sent on their way. They have the opportunity to speak with a banker who can explain how credit is built, why payment history matters, and how even a modest savings discipline—automated transfers of fifty or one hundred dollars per month—compounds meaningfully over time.
First-time credit products, including secured credit cards and small personal loans, serve an important function at this stage. Used responsibly, they establish the credit history that will eventually determine mortgage eligibility, business loan terms, and even rental applications. A community bank advisor can help a young adult understand the mechanics of credit utilization and the long-term cost of carrying a balance—lessons that a national bank's onboarding email sequence rarely delivers with the same clarity as a face-to-face conversation.
For young adults approaching their first home purchase, Bear State Bank's mortgage advisors can provide guidance that begins well before the loan application—reviewing savings rates, explaining down payment assistance programs available in the region, and helping customers understand what a realistic homebuying timeline looks like given their current financial profile.
Young Families: Balancing Competing Priorities
The years between thirty and fifty are frequently the most financially complex. Mortgage payments, childcare costs, career transitions, and the competing urgency of retirement savings and education funding all arrive simultaneously. It is the chapter in which financial stress is most common—and in which good guidance has the greatest practical impact.
Community banks are particularly well-suited to serve young families because their advisors can look at a household's complete financial picture rather than individual product categories. A Bear State Bank advisor working with a family managing a mortgage, a home equity line, a pair of 529 education savings accounts, and a small business operating line can coordinate those products in ways that reduce redundancy, optimize cash flow, and ensure that each instrument is serving its intended purpose.
The 529 college savings plan deserves particular attention at this stage. Contributions made during a child's early years benefit from the longest possible compounding runway. Bear State Bank advisors can help families understand state-specific tax advantages, contribution strategies, and how education savings interacts with financial aid calculations—nuances that matter significantly but are rarely communicated clearly by automated platforms.
This is also the period during which life insurance, disability coverage, and estate planning documents—wills, powers of attorney, beneficiary designations—become genuinely urgent. A community bank with established relationships across legal, insurance, and financial planning disciplines can facilitate referrals and help families approach these conversations systematically rather than reactively.
Established Adults: Accelerating Toward Retirement
By the time a household reaches its fifties, the financial picture often shifts from accumulation to optimization. Mortgages may be substantially paid down. Children may be approaching financial independence. Retirement accounts have had decades to grow, and the question of when and how to retire begins to move from abstract to concrete.
This is the chapter in which the depth of a banking relationship becomes most evident. A Bear State Bank advisor who has worked with a family for fifteen or twenty years brings an institutional memory that no new relationship can replicate. They know the family's risk tolerance, their history with debt, their real estate equity position, and the financial habits that have defined their trajectory.
Key planning priorities at this stage include maximizing contributions to tax-advantaged retirement accounts, reviewing asset allocation to ensure it reflects a shortening investment horizon, and modeling retirement income scenarios that account for Social Security timing, required minimum distributions, and healthcare costs. Bear State Bank's financial planning team can engage with customers on each of these dimensions, either directly or in coordination with affiliated advisors.
Small business owners in this phase face an additional layer of complexity: succession planning. Whether the goal is to sell the business, transfer it to a family member, or wind it down, the process requires careful coordination of legal, tax, and financial considerations. Our small business banking team has supported regional business owners through this transition and understands the emotional as well as financial dimensions of that process.
Seniors and Legacy Planning: Preserving What You've Built
Retirement and legacy planning represent the culmination of a lifetime of financial decisions. At this stage, the priorities shift again—from growth to preservation, from accumulation to distribution, and from personal financial security to the financial futures of children and grandchildren.
Community banks offer a meaningful advantage here because they understand family relationships in ways that national institutions cannot. When a Bear State Bank advisor sits down with a senior customer and their adult children to discuss estate planning, they bring familiarity with the family's history, values, and dynamics. That context shapes the conversation in ways that a generic estate planning worksheet cannot.
Practical considerations at this stage include the structure of beneficiary designations across all accounts, the potential benefits of trust accounts for asset protection and transfer efficiency, and the coordination of retirement income sources to minimize tax liability. For customers with charitable giving intentions, donor-advised funds and charitable remainder trusts offer structured mechanisms that align financial planning with philanthropic values.
Bear State Bank also recognizes that senior customers are disproportionately targeted by financial fraud. Our advisors are trained to identify warning signs and to have proactive conversations with customers and their families about protective measures—another benefit of a relationship that extends across years rather than transactions.
One Family, One Bank, Many Chapters
The financial journey of a family is not a series of disconnected transactions. It is a continuous narrative in which each chapter builds on the one before it. Bear State Bank's approach to multigenerational banking reflects that reality—offering personalized guidance that evolves as your family evolves, grounded in the kind of long-term relationship that only a community bank can provide.
We invite families at every stage of their financial journey to connect with a Bear State Bank advisor. Whether you are helping a young adult open her first account, navigating the competing demands of family financial life, or planning the legacy you intend to leave, we are here for every chapter. Visit bearstatebank.com or stop by your nearest branch to begin the conversation.