The Fraud Nobody Talks About: Breaking the Silence Around Check Scams in Rural America
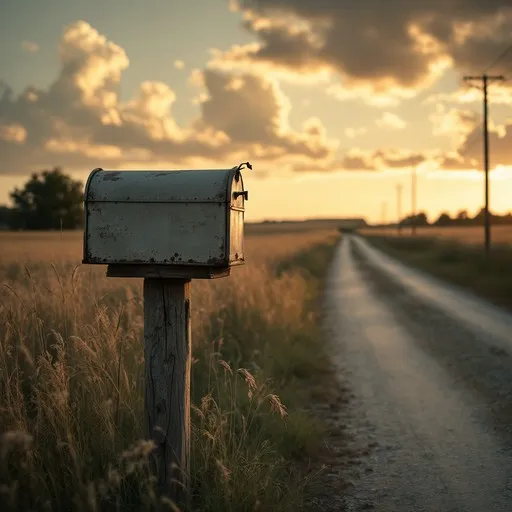
Photo: empty rural curbside mailbox on country road at dusk, via images.stockcake.com
The scheme is almost laughably low-tech in an age of encrypted payments: steal mail from a curbside box, wash the ink off a check with household chemicals, rewrite the payee and the amount, and cash it. Yet check fraud is rising sharply across the United States, and the people hit hardest are often those least equipped to fight back — older adults on fixed incomes and residents of rural communities who still rely on the mail for bill payment and government benefits.
What's more troubling than the crime itself is its shadow economy of silence. A large share of victims never report it at all.
Why Victims Stay Quiet
The reasons are human and predictable. Embarrassment heads the list. Many older victims grew up in an era when being defrauded carried a stigma — the implication that you were careless, gullible, slipping. Rather than tell their children or their banker, they absorb the loss or quietly cover it from savings.
Confusion compounds the shame. When a washed check clears, the victim often doesn't immediately understand what happened. Was it the payee? The post office? The bank? The dispute process can feel labyrinthine, with affidavit forms, liability questions, and deadlines that aren't explained in plain language. Rural victims face an additional barrier: the nearest branch may be a long drive away, and the nearest federal reporting channel is a website they may not use.
The result is a crime that systematically under-reports itself — which means it also under-prioritizes itself in enforcement and in institutional planning.
What Responsible Banks Owe Their Customers
This is where opinion becomes necessary: banks know where the vulnerabilities are, and too many have treated check fraud as the customer's problem to detect. That posture is indefensible. A financial institution that profits from a customer's trust owes that customer a defense. Concretely, that means:
Proactive anomaly alerts. Flagging out-of-pattern check activity — a payee never seen before, an amount far outside the customer's history, checks clearing from a distant geography — and contacting the customer immediately, not after funds are gone.
In-person verification for high-risk transactions. When an elderly customer walks in wanting to withdraw or wire an unusual sum, trained staff should slow the transaction down, ask questions, and involve family when appropriate. Scammers exploit speed; a teller who knows the customer is the best circuit breaker in the system.
Plain-language fraud education. Not a PDF buried on a website, but community workshops — at senior centers, churches, grange halls, farm bureaus — that explain check washing, fake check overpayment scams, and mailbox theft in terms a neighbor would use. Small businesses, which often handle checks for invoices and payroll, need this education as much as individuals.
Easy, dignified reporting. A victim who calls their bank should reach a person quickly, get the dispute process explained step by step, and never be made to feel foolish. Every unreported fraud is a fraud the institution can't pattern-match against.
Why Local Accountability Matters Most
National banks process fraud at scale, and scale breeds anonymity — a fraud claim becomes a case number routed to a call center three time zones away. A community bank operates differently by design. The teller may recognize the customer's handwriting. The branch manager may know that the customer's late husband always signed checks a certain way. That relational knowledge is not sentimentality; it is fraud detection that no algorithm has replicated.
Local accountability also means local consequence. A community bank that handles a customer's fraud poorly answers for it at the church picnic and the chamber of commerce meeting. That pressure produces better behavior than any regulatory fine.
A Closing Word to Victims
If you have been defrauded, the shame belongs to the criminal, not to you. These schemes are engineered by organized networks, and they succeed against smart, careful people every day. Report it to your bank, your local sheriff's office, and the U.S. Postal Inspection Service. Every report makes the next scam harder to run.
And to the institutions that serve our towns and main streets: the quiet victims in your communities are watching how you respond. Fraud prevention isn't a product feature. It's the practical expression of the trust your charter was built on.